The Smart Investor’s Guide to What Is a Roth Conversion
A Roth IRA conversion isn’t just another financial buzzword—it’s a tactical move that can reshape how you approach retirement savings. At its core, what is a Roth conversion boils down to a deliberate shift of funds from a traditional IRA or 401(k) into a Roth IRA, paying taxes upfront in exchange for tax-free growth down the line. But the real power lies in the flexibility: converting now could mean avoiding higher tax brackets later, or seizing a low-income year to minimize the tax hit. The strategy isn’t one-size-fits-all; it demands precision, timing, and a deep understanding of how tax laws interact with your long-term goals.
What makes this maneuver particularly compelling is its dual nature—part tax planning, part wealth preservation. Imagine paying taxes on a sum today that would otherwise balloon in a future high-tax environment. That’s the essence of a Roth conversion strategy. Yet, missteps—like converting too aggressively or ignoring income limits—can turn a smart play into a costly mistake. The key is balance: leveraging the conversion’s potential without triggering unintended tax consequences or penalties.
For high earners, early retirees, or those nearing a lower-income phase, what is a Roth conversion can be the difference between a retirement fund that shrinks under taxes and one that thrives. But the rules are nuanced. The conversion window, income thresholds, and even the type of IRA you’re converting from all play critical roles. This isn’t just about moving money—it’s about optimizing it for a future where tax rates, market conditions, and personal circumstances may look entirely different.

The Complete Overview of What Is a Roth Conversion
A Roth IRA conversion is the process of transferring funds from a tax-deferred retirement account—such as a traditional IRA, SEP IRA, or 401(k)—into a Roth IRA. The critical distinction is that contributions to a traditional IRA are made with pre-tax dollars, meaning taxes are deferred until withdrawals in retirement. In contrast, Roth IRA contributions are made with after-tax dollars, but qualified withdrawals in retirement are entirely tax-free. When you perform a Roth conversion, you’re essentially paying taxes on the converted amount today, allowing the funds to grow tax-free thereafter.
The appeal of this strategy lies in its ability to hedge against future tax uncertainty. If Congress raises tax rates—or if you anticipate being in a higher tax bracket in retirement—a Roth conversion can lock in today’s lower rates. Additionally, Roth IRAs offer no required minimum distributions (RMDs), providing more control over inheritance planning. However, the conversion itself triggers a taxable event, meaning you’ll owe income tax on the converted amount in the year it occurs. This is why timing, asset allocation, and tax bracket management are paramount.
Historical Background and Evolution
The Roth IRA, named after Senator William Roth, was introduced as part of the Taxpayer Relief Act of 1997. Its creation was a response to the growing concern over rising tax rates and the need for tax-free retirement vehicles. Initially, the Roth IRA was limited to individuals with incomes below $95,000 (single filers) or $150,000 (joint filers), but these limits were gradually adjusted over time. The Pension Protection Act of 2006 eliminated income limits for conversions, making the Roth IRA more accessible to higher earners.
Table of Contents
- The Complete Overview of What Is a Roth Conversion
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can I convert a 401(k) to a Roth IRA?
- Q: What are the income limits for a Roth IRA conversion?
- Q: How do I avoid paying taxes twice on a Roth conversion?
- Q: Can I undo a Roth conversion?
- Q: What happens if I convert too much and get pushed into a higher tax bracket?
- Q: Are there penalties for converting a Roth IRA?
Over the years, the strategy of converting to a Roth IRA has evolved from a niche tactic to a mainstream financial planning tool. The Great Recession of 2008-2009, for instance, saw a surge in conversions as investors took advantage of lower asset values and tax rates. More recently, the Tax Cuts and Jobs Act of 2017 temporarily lowered tax rates, prompting many to convert larger sums before rates potentially rose again. Today, the approach is often tailored to individual circumstances, such as retirement timing, estate planning goals, or market conditions.
Core Mechanisms: How It Works
The mechanics of a Roth IRA conversion are straightforward but require careful execution. To initiate the process, you instruct your IRA custodian to transfer funds from your traditional IRA (or another eligible account) into a Roth IRA. This transfer is typically taxable, as the IRS treats it as a distribution. You’ll receive a 1099-R form reporting the taxable amount, which must be included in your gross income for the year. However, you have the option to spread the tax liability over two years if you meet specific requirements, such as converting a traditional IRA to a Roth IRA.
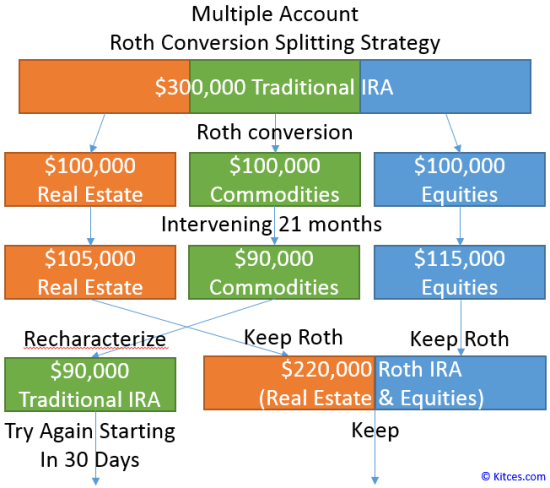
Once the funds are in the Roth IRA, they begin growing tax-free. To avoid early withdrawal penalties, you must adhere to the Roth IRA’s five-year rule: withdrawals of earnings are tax-free only if the Roth IRA has been open for at least five years or if you’re age 59½ or older. This rule underscores the importance of long-term planning when considering a Roth conversion strategy. Additionally, converted funds cannot be recharacterized (undone) after 2018, adding another layer of permanence to the decision.
Key Benefits and Crucial Impact
A Roth IRA conversion isn’t just a tax move—it’s a wealth-preservation strategy that can significantly alter your financial trajectory. By paying taxes today, you eliminate the risk of higher future tax rates, inflation eroding your purchasing power, or unexpected tax law changes. This is particularly valuable for those who expect to be in a higher tax bracket in retirement or who want to leave a tax-free legacy to heirs. The conversion also provides flexibility, as Roth IRAs are not subject to RMDs, allowing you to defer withdrawals indefinitely.
For investors who have maxed out their traditional IRA contributions or those who have inherited IRAs, a Roth conversion can be a way to optimize tax efficiency. It’s also a powerful tool for estate planning, as beneficiaries of a Roth IRA inherit the account tax-free, provided they follow the rules. However, the benefits are not without trade-offs. The upfront tax bill can be substantial, and converting too much in a single year could push you into a higher tax bracket, negating some of the advantages.
"A Roth conversion is like buying fire insurance—you hope you never need it, but if you do, it’s invaluable. The key is to structure it in a way that minimizes the cost while maximizing the long-term benefit."
— David McKnight, CFP® and Founder of True Wealth Design
Major Advantages
- Tax-Free Growth: All future earnings in the Roth IRA grow tax-free, providing a significant advantage in high-tax retirement scenarios.
- No RMDs: Unlike traditional IRAs, Roth IRAs have no required minimum distributions, allowing you to defer withdrawals and let your money compound longer.
- Estate Planning Flexibility: Beneficiaries inherit a Roth IRA tax-free, making it an efficient tool for passing wealth to heirs.
- Bracket Management: Converting in a low-income year can reduce the tax impact, allowing you to pay taxes at a lower rate.
- Legacy Planning: Since Roth IRAs are not subject to stretch IRA rules (for non-spousal beneficiaries), heirs can withdraw funds over their lifetime, preserving the tax-free status.

Comparative Analysis
| Traditional IRA | Roth IRA (Post-Conversion) |
|---|---|
| Tax-deferred growth; taxes paid in retirement. | Tax-free growth; no taxes on qualified withdrawals. |
| Subject to RMDs starting at age 73 (2024 rules). | No RMDs; withdrawals can be deferred indefinitely. |
| Income tax deductions may be available (depending on income). | No upfront tax deductions; contributions are after-tax. |
| Penalties for early withdrawals (with exceptions). | Contributions can be withdrawn penalty-free; earnings have a five-year rule. |
Future Trends and Innovations
The landscape of Roth IRA conversions is likely to evolve alongside changes in tax policy, market conditions, and retirement planning trends. One emerging trend is the use of what is a Roth conversion as part of a broader tax-loss harvesting strategy. By converting in years when the market is down, investors can offset capital gains with the taxable conversion amount, further reducing their tax burden. Additionally, as more states adopt pass-through entity taxes, the appeal of Roth conversions may grow for high-net-worth individuals seeking to minimize state tax liabilities.
Another innovation is the rise of "mega backdoor Roth" strategies, where investors contribute after-tax dollars to a 401(k) and then convert those funds to a Roth IRA. This approach allows high earners to bypass income limits and maximize tax-free growth. As the gig economy expands and more individuals work independently, the need for flexible retirement planning tools like Roth conversions will only increase. Staying ahead of these trends will be crucial for investors looking to optimize their tax efficiency in the decades ahead.
Conclusion
A Roth IRA conversion is more than a financial transaction—it’s a strategic decision that can redefine your retirement outlook. By understanding what is a Roth conversion and its nuances, you can align your tax planning with your long-term goals, whether that means avoiding higher tax rates, leaving a tax-free legacy, or simply gaining more control over your retirement income. The key is to approach the conversion with a clear plan, considering your current tax bracket, future income expectations, and market conditions.
For many, the ideal time to convert is during a low-income year or when asset values are depressed, but the optimal strategy varies by individual. Consulting with a tax advisor or financial planner can help you navigate the complexities and ensure the conversion aligns with your broader financial objectives. In an era of uncertainty, tax-efficient strategies like Roth conversions offer a rare opportunity to take control of your financial future.
Comprehensive FAQs
Q: Can I convert a 401(k) to a Roth IRA?
A: Yes, but you must first roll over the 401(k) funds into a traditional IRA before converting to a Roth IRA. Direct conversions from a 401(k) to a Roth IRA are not allowed unless your employer plan permits in-service distributions.
Q: What are the income limits for a Roth IRA conversion?
A: There are no income limits for converting to a Roth IRA, but you may be subject to the provisional income limits that affect your ability to contribute directly to a Roth IRA. However, converting from a traditional IRA or 401(k) is always an option, regardless of income.
Q: How do I avoid paying taxes twice on a Roth conversion?
A: You won’t pay taxes twice if you follow the rules correctly. The conversion itself is taxed once, and future withdrawals (if qualified) are tax-free. The key is ensuring you meet the five-year holding period and age requirements to avoid penalties or additional taxes.
Q: Can I undo a Roth conversion?
A: No, as of 2018, the IRS no longer allows recharacterizations (undoing a Roth conversion). Before that year, you could reverse the conversion within 60 days, but this option is no longer available.
Q: What happens if I convert too much and get pushed into a higher tax bracket?
A: If your conversion causes you to exceed income thresholds for tax credits or deductions, you may owe additional taxes. To mitigate this, consider converting gradually over multiple years or using a strategy like the "backdoor Roth" to spread out the tax impact.
Q: Are there penalties for converting a Roth IRA?
A: There are no penalties for converting to a Roth IRA, but early withdrawals of earnings (before age 59½ or the five-year rule) may incur a 10% penalty, unless an exception applies (e.g., first-time home purchase or disability).
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Bevvy.