Navigating the Modern Landscape: Your Payment Comprehensive Guide to Billing Options
Every transaction—whether a recurring subscription, a one-time purchase, or an automated payment—relies on a system that balances efficiency with precision. Behind the scenes, billing infrastructure determines whether a business retains customers or loses them to friction, while consumers face the silent frustration of mismatched payment schedules or unexpected fees. The stakes are higher than ever: a 2023 study revealed that 68% of consumers abandon carts due to billing complexities, yet most businesses still rely on outdated payment comprehensive guide billing options that fail to adapt.
What separates a seamless payment experience from a chaotic one isn’t just technology—it’s the strategic alignment of billing methods with user behavior. Take the rise of "pay-as-you-go" models in SaaS, where businesses now offer granular billing cycles (monthly, annual, or usage-based) to match customer cash flow. Meanwhile, fintech startups have dismantled traditional invoicing by embedding AI-driven payment reminders and dynamic pricing tiers. The question isn’t whether to modernize billing systems, but how quickly—and whether legacy providers can keep pace.
This guide dissects the anatomy of payment billing options, from their historical roots to the cutting-edge innovations reshaping industries. Whether you’re a merchant optimizing conversions or a consumer navigating subscription traps, understanding these systems is no longer optional—it’s a competitive advantage.

The Complete Overview of Payment Comprehensive Guide Billing Options
The term payment comprehensive guide billing options encompasses the full spectrum of methods businesses and financial institutions use to process, schedule, and recover payments. At its core, it’s a framework that dictates how money moves between parties—whether through direct debits, credit card authorizations, or blockchain-based smart contracts. The evolution from manual ledgers to real-time API-driven billing reflects broader shifts in trust, automation, and consumer expectations.
Today, billing options aren’t just transactional tools; they’re strategic levers. A subscription-based business might offer tiered pricing with flexible billing cycles to reduce churn, while a B2B vendor could implement net-30 terms to improve cash flow. The wrong choice—like rigid annual contracts for a startup—can trigger cancellations, while the right one (e.g., microtransactions for gamers) turns payments into a frictionless experience. The challenge lies in selecting options that align with both operational needs and customer psychology.
Historical Background and Evolution
The origins of billing trace back to the 19th century, when merchants relied on handwritten invoices and cash-on-delivery models. The 1950s introduced charge cards (forerunners to credit cards), but true billing innovation arrived with the 1970s’ rise of automated clearing houses (ACH), enabling direct deposits and recurring payments. By the 1990s, the internet democratized billing options: PayPal (1998) and Stripe (2010) transformed one-time purchases into subscription ecosystems, while companies like Zuora pioneered comprehensive billing solutions for SaaS.
Table of Contents
- The Complete Overview of Payment Comprehensive Guide Billing Options
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How do I choose between subscription and invoice-based billing?
- Q: What are the risks of automated dunning systems?
- Q: Can I offer multiple billing options for the same product?
- Q: How does tokenization improve payment security?
- Q: What’s the difference between proration and amortization in billing?
Fast-forward to 2024, and the landscape is unrecognizable. Open banking regulations now allow third-party payment processors to access bank data, enabling "invisible billing" where transactions occur without user interaction. Meanwhile, decentralized finance (DeFi) platforms are experimenting with tokenized billing, where payments are tied to blockchain events. The historical arc reveals a clear trend: billing options have shifted from transactional to experiential, from rigid to adaptive, and from opaque to transparent.
Core Mechanisms: How It Works
Under the hood, payment billing options operate through a combination of technical and contractual layers. For credit/debit cards, the process involves authorization (checking funds), capture (reserving charges), and settlement (finalizing transactions) across networks like Visa or Mastercard. Recurring billing, meanwhile, relies on tokens (stored card details) or direct bank integrations to automate future payments, while dunning management systems handle failed attempts with escalating reminders.
Subscription models add complexity: they often use "proration" to adjust charges for mid-cycle upgrades/downgrades, and "revenue recognition" rules to account for deferred revenue under GAAP. Meanwhile, invoice-based systems (common in B2B) may incorporate payment terms like "net-15" or "due upon receipt," with late fees kicking in after a grace period. The mechanics vary by industry—healthcare might use HIPAA-compliant billing, while e-commerce leans on fraud detection algorithms to flag suspicious transactions.
Key Benefits and Crucial Impact
Effective billing isn’t just about collecting payments; it’s about reducing friction, improving cash flow, and even driving customer loyalty. Businesses that deploy the right comprehensive billing options see lower cart abandonment rates, higher average order values, and reduced administrative overhead. For consumers, the impact is equally significant: flexible billing cycles can ease budgeting stress, while transparent fee structures build trust. The ripple effects extend to financial health—companies with optimized billing recover receivables faster, while individuals avoid late penalties through automated systems.
Yet the benefits are asymmetrical. A poorly designed billing system can erode trust faster than any marketing campaign. Consider the backlash against "surprise billing" in healthcare, where patients faced unexpected charges for out-of-network providers. Or the frustration of subscription fatigue, where users cancel services after encountering unclear cancellation policies. The stakes are clear: billing options are no longer a back-office function but a frontline customer experience.
"Billing is the silent UX of finance—when it works, no one notices; when it fails, it’s all anyone talks about." — Jane Thompson, Head of Payments at FinTech Innovations
Major Advantages
- Reduced Churn: Flexible billing cycles (e.g., monthly vs. annual) accommodate varying budgets, cutting voluntary cancellations by up to 40%.
- Automation Efficiency: AI-driven dunning systems reduce manual follow-ups by 60%, lowering operational costs.
- Global Scalability: Multi-currency billing options expand market reach without requiring local bank accounts.
- Fraud Mitigation: Real-time transaction monitoring (e.g., 3D Secure 2.0) reduces chargebacks by 25–30%.
- Data-Driven Insights: Analytics tied to billing behavior reveal purchasing patterns, enabling personalized offers.
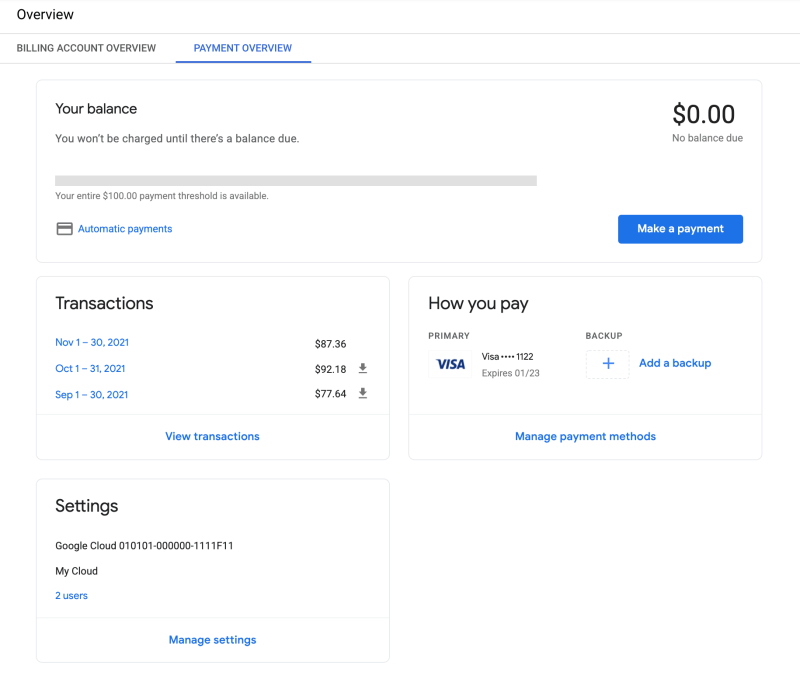
Comparative Analysis
| Billing Option | Best Use Case |
|---|---|
| Subscription Billing | SaaS, streaming services, memberships. Ideal for predictable revenue with flexible tiers (e.g., "pay-as-you-go" add-ons). |
| Invoice-Based Billing | B2B, healthcare, professional services. Works for large transactions with payment terms (e.g., net-30) and tax compliance. |
| Microtransactions | Gaming, content platforms. Enables low-value, high-frequency payments (e.g., in-game purchases) with minimal friction. |
| Tokenized Payments | E-commerce, marketplaces. Stores payment details securely for one-click checkouts, reducing cart abandonment. |
Future Trends and Innovations
The next decade of payment billing options will be defined by three forces: personalization, interoperability, and regulatory pressure. AI will move beyond basic dunning to predict optimal billing cycles based on user spending habits, while open banking APIs will enable "invisible billing" where payments sync automatically with bank accounts. Meanwhile, central bank digital currencies (CBDCs) could introduce programmable money—where bills are tied to smart contracts (e.g., "pay only if X condition is met").
Regulatory shifts will also reshape the landscape. The EU’s Payment Services Directive (PSD2) and U.S. consumer protection laws are pushing for more transparency in billing, while anti-fraud measures like "strong customer authentication" (SCA) will complicate but also secure transactions. The winners in this space won’t just offer more billing options—they’ll redefine how payments feel, blending seamlessness with security.

Conclusion
The payment comprehensive guide billing options you choose today will determine your financial agility tomorrow. For businesses, the shift from static invoices to dynamic, data-driven billing is inevitable; those who resist risk falling behind in customer retention and revenue predictability. Consumers, meanwhile, demand nothing less than frictionless, transparent, and adaptive systems—whether that’s a gym membership auto-pausing during travel or a utility bill adjusting based on usage.
As the line between financial services and customer experience blurs, billing is no longer a back-office concern but a strategic asset. The companies that thrive will be those who treat billing as a conversation—not a transaction—balancing automation with human touch, and innovation with compliance. The future isn’t just about processing payments; it’s about making them disappear.
Comprehensive FAQs
Q: How do I choose between subscription and invoice-based billing?
A: Subscription billing suits recurring revenue models (e.g., software, streaming) where predictability matters, while invoice-based billing works for one-time or high-value transactions (e.g., B2B sales). Key factors: customer payment frequency, revenue recognition needs, and administrative overhead. Many businesses use hybrid models (e.g., annual subscriptions with monthly invoices).
Q: What are the risks of automated dunning systems?
A: Over-aggressive dunning can damage customer relationships, while under-performing systems may fail to recover payments. Risks include: alienating users with excessive reminders, missing fraudulent attempts, or violating privacy laws (e.g., GDPR). Best practice: Use AI to personalize communication (e.g., "We noticed your balance—here’s a discount for settling now") and comply with local regulations.
Q: Can I offer multiple billing options for the same product?
A: Yes, and it’s increasingly common. For example, a SaaS company might offer monthly, annual, or usage-based billing, while an e-commerce store could provide "pay-in-full" or "interest-free installments." The challenge is managing complexity—ensure your backend supports dynamic pricing, proration, and revenue recognition without errors. Tools like Chargebee or Zuora specialize in this flexibility.
Q: How does tokenization improve payment security?
A: Tokenization replaces sensitive card details with unique identifiers (tokens), reducing exposure during transactions. Even if a token is stolen, it’s useless without the underlying card data. This is why one-click checkouts (e.g., Amazon Pay) and saved payment methods work securely. Compliance with PCI DSS Level 1 is mandatory for tokenization, and providers like Stripe or Braintree handle the encryption.
Q: What’s the difference between proration and amortization in billing?
A: Proration adjusts charges for mid-cycle changes (e.g., upgrading a subscription halfway through the month), while amortization spreads costs over time (e.g., capitalizing a large purchase). Proration is common in SaaS (e.g., "You’ll be charged $X for the remaining days"), while amortization appears in accounting for assets like equipment. Both require careful handling to avoid revenue misclassification under GAAP or IFRS.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Bevvy.