The Hidden Power of What Is an Income Statement: Why It Rules Business Finance
The numbers don’t lie—but they’re only as useful as your ability to read them. At its core, what is an income statement boils down to a single, uncompromising question: How much money did this business actually make? Yet the answer isn’t just a profit figure. It’s a narrative of revenue, expenses, and the hidden costs that turn a promising balance sheet into a financial black hole. Every line tells a story—whether it’s the creeping drag of operational inefficiencies or the sudden spike in R&D spending that signals a bet on future growth.
Most business owners glance at the bottom line and assume the work is done. They miss the subtleties: the difference between gross profit and net income, the weight of non-recurring items, or how aggressive (or desperate) a company’s revenue recognition policies might be. These details separate the savvy investor from the speculator, the disciplined CEO from the reactive one. The income statement isn’t just a document—it’s a mirror reflecting a company’s health, strategy, and resilience under pressure.

The Complete Overview of What Is an Income Statement
An income statement—often called the profit and loss (P-L) statement—is the financial report that distills a company’s performance over a specific period, typically a quarter or fiscal year. Unlike the balance sheet, which captures a snapshot in time, or the cash flow statement, which tracks liquidity, the income statement is a dynamic record of revenue generation and expense management. It answers the fundamental question: Did the business earn more than it spent? But the depth of its insights lies in the granularity: Was the profit sustainable? Were costs controlled, or were they inflated by one-time hits? The statement’s structure—revenue minus costs of goods sold (COGS), minus operating expenses, minus taxes—reveals not just profitability, but the quality of that profitability.What sets the income statement apart is its role as the bridge between accounting theory and real-world decision-making. Investors use it to project future earnings; creditors rely on it to assess repayment risk; and executives leverage it to justify capital allocation. Yet its power is often underestimated because the language of finance—terms like EBITDA, non-GAAP adjustments, or extraordinary items—can obscure the raw truth: a company’s ability to convert sales into sustainable profit. The statement’s true value emerges when analyzed in context: comparing year-over-year trends, dissecting margin changes, and cross-referencing with cash flow data to separate accounting profits from actual cash generation.
Historical Background and Evolution
The concept of what is an income statement traces back to the 19th century, when industrialization demanded more rigorous financial tracking. Early versions were rudimentary—merely listing revenues and expenses—but as corporations grew in complexity, so did the need for standardization. The rise of limited liability companies in the early 1900s accelerated this evolution, as shareholders required transparency to trust management with their capital. By the 1930s, accounting frameworks like the Generally Accepted Accounting Principles (GAAP) in the U.S. and International Financial Reporting Standards (IFRS) globally formalized the income statement’s structure, ensuring consistency across industries.The post-World War II era saw the income statement transform from a compliance tool into a strategic asset. The 1970s and 1980s brought innovations like segment reporting, allowing companies to disclose performance by product lines or geographic regions—a critical development for multinational corporations. Meanwhile, the dot-com bubble of the late 1990s exposed flaws in revenue recognition practices, leading to stricter rules (e.g., ASC 605 and later ASC 606) that forced companies to align income statements with actual economic activity. Today, the statement is not just a historical record but a real-time indicator of operational agility, with innovations like XBRL tagging enabling instant data analysis.
Core Mechanisms: How It Works
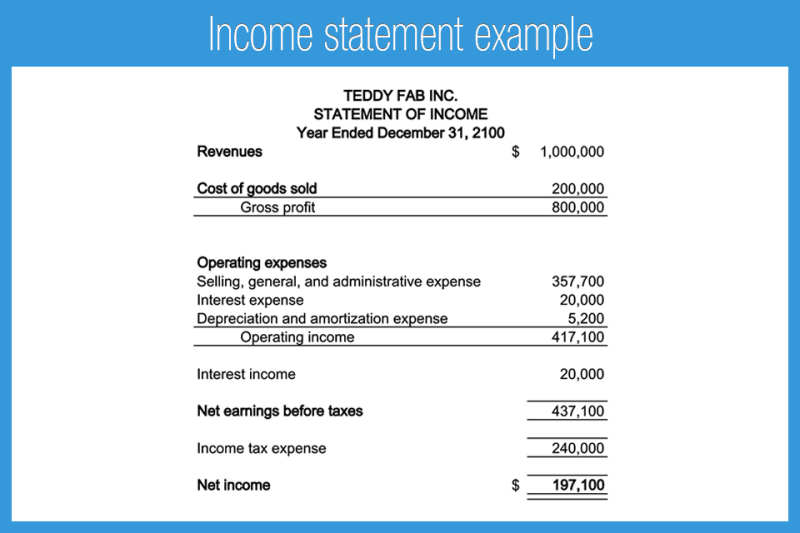
The income statement’s mechanics are deceptively simple: it starts with total revenue (sales minus returns and discounts), subtracts the cost of goods sold (COGS) to arrive at gross profit, then deducts operating expenses (salaries, rent, marketing) to reach operating income (EBIT). From there, interest, taxes, and non-operating items (e.g., investment gains) are factored in to land on net income. Yet the devil lies in the details: How is revenue recognized? Are expenses capitalized or expensed immediately? Are there one-time charges masking recurring issues?The statement’s power lies in its ability to highlight financial health through key ratios. Gross margin (gross profit/revenue) reveals pricing power; operating margin (EBIT/revenue) shows efficiency; and net margin (net income/revenue) reflects overall profitability. But these metrics are only as reliable as the data behind them. Aggressive revenue recognition (e.g., recognizing sales before delivery) can inflate top-line growth, while aggressive expense management (e.g., deferring maintenance costs) can hide long-term liabilities. The income statement’s true value is in its ability to force these trade-offs into the open.
Key Benefits and Crucial Impact
Few financial tools offer as much insight into a business’s viability as what is an income statement. For entrepreneurs, it’s a reality check: Are your pricing models sustainable? For investors, it’s a litmus test: Does the company’s growth translate to actual profitability? And for creditors, it’s a risk assessment: Can this borrower service its debt? The statement’s impact extends beyond internal use—it shapes public perception, influencing stock valuations, credit ratings, and even regulatory scrutiny. A single red flag (e.g., shrinking margins, rising R&D as a percentage of revenue) can send analysts scrambling to reassess a company’s prospects.Table of Contents
- The Complete Overview of What Is an Income Statement
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How often should a business review its income statement?
- Q: Can a company have positive net income but negative cash flow?
- Q: What’s the difference between EBIT and EBITDA?
- Q: Why do some companies report "non-GAAP" earnings?
- Q: How does inflation affect an income statement?
- Q: Can an income statement predict bankruptcy?
The income statement’s role in corporate governance cannot be overstated. It holds executives accountable by quantifying the results of their strategies. A declining net margin might signal over-expansion; a spike in non-GAAP adjustments could indicate earnings manipulation. In an era where stakeholders demand ESG (Environmental, Social, Governance) transparency, the income statement has evolved to include metrics like carbon costs or social impact expenses, blending traditional finance with modern priorities.
"An income statement is not just a snapshot—it’s a story of how a company turns resources into value, and how well it withstands the pressures of competition, inflation, and market volatility." — Warren Buffett (adapted from Berkshire Hathaway’s financial disclosures)
Major Advantages
- Profitability Assessment: Directly measures whether revenue exceeds expenses, providing a clear profitability benchmark.
- Operational Efficiency Insights: Margins (gross, operating, net) reveal how effectively a company controls costs relative to sales.
- Investor Confidence Builder: Transparent income statements reduce information asymmetry, attracting capital and lowering cost of capital.
- Strategic Decision-Making Tool: Identifies areas for cost optimization (e.g., high overhead) or revenue growth (e.g., underperforming product lines).
- Regulatory and Tax Compliance: Ensures adherence to accounting standards, avoiding legal penalties and financial restatements.
Comparative Analysis
| Income Statement | Balance Sheet |
|---|---|
| Focuses on revenue and expenses over time (dynamic). | Shows assets, liabilities, and equity at a point in time (static). |
| Key metric: Net income (profit/loss). | Key metric: Book value (equity). |
| Used to assess operational performance and sustainability. | Used to evaluate financial health and solvency. |
| Limitation: Does not reflect cash flow (accrual accounting). | Limitation: Does not show liquidity (e.g., illiquid assets). |
Future Trends and Innovations
The income statement is evolving alongside digital transformation. Artificial intelligence is now used to flag anomalies in expense patterns, while blockchain is being tested for immutable revenue recognition records. Regulators are pushing for integrated reporting, merging financial and non-financial metrics (e.g., sustainability costs) into a single statement. Meanwhile, the rise of subscription-based models is forcing companies to adopt deferred revenue accounting, where income is recognized over time rather than upfront—a shift that will reshape how income statements are interpreted.Another frontier is real-time financial reporting, where companies update income statements dynamically (e.g., monthly instead of quarterly) to reflect market changes instantly. However, this trend raises questions about data accuracy and the potential for overreacting to short-term volatility. As ESG criteria gain prominence, income statements may soon include social return on investment (SROI) metrics, blending traditional finance with impact measurement. The future of what is an income statement isn’t just about numbers—it’s about telling a more holistic story of value creation.

Conclusion
Understanding what is an income statement is more than an accounting exercise—it’s a gateway to financial literacy. Whether you’re an entrepreneur scrutinizing your own P-L statement or an investor dissecting a Fortune 500’s earnings call, the insights lie in the details: the margin trends, the expense ratios, the non-recurring items buried in the footnotes. The statement’s true power emerges when it’s used not as a static report, but as a dynamic tool for course correction, strategy refinement, and risk management.In an era where financial data is abundant but context is scarce, the income statement remains the most direct line to a company’s soul. It doesn’t lie—but it does demand attention. Ignore it at your peril.
Comprehensive FAQs
Q: How often should a business review its income statement?
A: Ideally, monthly for small businesses and quarterly for larger enterprises. Monthly reviews help catch cash flow issues early, while quarterly aligns with investor reporting cycles. Annual deep dives are critical for long-term strategy.
Q: Can a company have positive net income but negative cash flow?
A: Yes. Net income is an accrual-based metric (recognizing revenue when earned, expenses when incurred), while cash flow tracks actual inflows/outflows. For example, a company might recognize revenue upfront (positive net income) but delay payments to suppliers (negative cash flow).
Q: What’s the difference between EBIT and EBITDA?
A: EBIT (Earnings Before Interest and Taxes) measures operating profit excluding interest and taxes. EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) adds back non-cash expenses (depreciation/amortization) to reflect cash-generating ability. EBITDA is often used for leverage ratios but can mask capital expenditures.
Q: Why do some companies report "non-GAAP" earnings?
A: Non-GAAP earnings exclude items like stock-based compensation, restructuring costs, or one-time charges to highlight "core" profitability. While useful for comparability, they can be manipulated—always compare GAAP and non-GAAP side by side.
Q: How does inflation affect an income statement?
A: Inflation distorts COGS (higher raw material costs) and operating expenses (labor, rent), compressing margins. Revenue may also rise nominally but lag inflation-adjusted demand. Companies in high-inflation sectors (e.g., energy, commodities) often use hedging strategies to stabilize income statements.
Q: Can an income statement predict bankruptcy?
A: Indirectly. Declining revenues, shrinking margins, rising debt-to-EBITDA ratios, and negative net income are red flags. However, cash flow statements and balance sheet liquidity are stronger predictors. The income statement’s role is to signal financial distress after it begins.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Bevvy.