What Is the Difference Between Gross Pay and Net Pay? The Hidden Math Behind Your Paycheck
The moment you accept a job offer, the excitement of a new salary often fades when you see your first paycheck—and realize it’s less than promised. That discrepancy isn’t a mistake. It’s the difference between what is the difference between gross pay and net pay, a fundamental concept that governs how much of your earnings you actually take home. Gross pay is the total amount an employer agrees to pay you for your work, while net pay is what remains after taxes, benefits, and other mandatory deductions. For many, this gap feels like an abstract puzzle, but understanding it isn’t just about numbers—it’s about financial control, tax planning, and even career decisions.
Take, for example, a software engineer earning $120,000 annually. On paper, that’s a lucrative salary, but after federal, state, Social Security, Medicare, and retirement contributions, their net pay might drop to $85,000—or less, depending on location and benefits. The same principle applies to hourly workers, freelancers, and even executives. The confusion arises because what is the difference between gross pay and net pay isn’t just about taxes; it’s a reflection of how employers, governments, and financial systems interact. Missteps here can lead to budgeting errors, missed savings opportunities, or even legal trouble during audits. Yet, despite its critical role in personal finance, this topic remains oversimplified in most workplaces.
The irony is that the answer lies in a system designed to be transparent—yet rarely explained clearly. Payroll departments, tax codes, and employer benefits packages are built on layers of deductions, each with its own rules, thresholds, and exceptions. A freelancer’s net pay, for instance, might include self-employment taxes, while a W-2 employee’s deductions are pre-calculated by their employer. The result? Two people earning the same gross income could see wildly different net amounts. To navigate this, you need more than a basic understanding—you need a breakdown of how each deduction works, why some are fixed and others variable, and how to optimize your take-home pay before the paycheck even arrives.
The Complete Overview of What Is the Difference Between Gross Pay and Net Pay
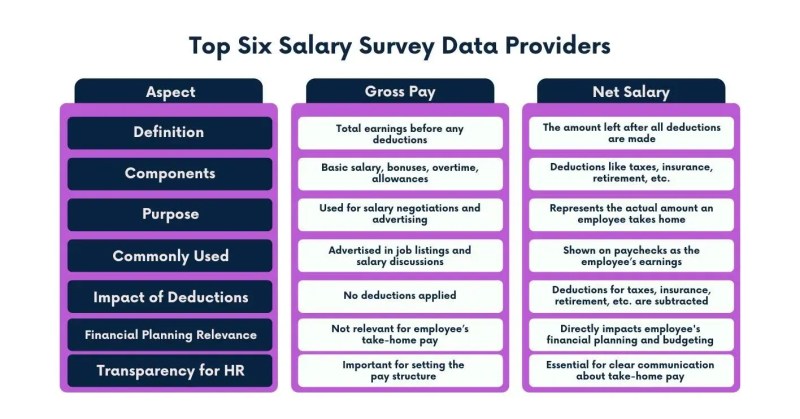
At its core, what is the difference between gross pay and net pay boils down to two financial states: the amount you’re paid before any reductions (gross) and the amount you receive after all legal and voluntary deductions (net). Gross pay is straightforward—it’s the total compensation for your labor, including base salary, bonuses, commissions, overtime, and sometimes even non-monetary benefits like stock options or housing stipends. Net pay, however, is the reality of your paycheck, after federal income tax, state income tax (where applicable), Social Security tax (6.2% up to the wage base limit), Medicare tax (1.45%, with an additional 0.9% for high earners), and other withholdings like retirement contributions, health insurance premiums, or union dues.
The transition from gross to net isn’t linear. It’s a series of calculations that vary by jurisdiction, employer policies, and individual circumstances. For example, a California resident earning $100,000 gross might see a larger net pay reduction than a Texas resident earning the same amount, thanks to state income taxes and local payroll taxes. Meanwhile, a remote worker in a no-income-tax state could keep a higher percentage of their gross pay—until they factor in self-employment taxes if they’re freelancing. The key insight here is that what is the difference between gross pay and net pay isn’t just a mathematical subtraction; it’s a reflection of the financial ecosystem you operate within.
Historical Background and Evolution
The distinction between gross and net pay traces back to the early 20th century, when income taxation became institutionalized. Before the 16th Amendment to the U.S. Constitution (ratified in 1913), which legalized federal income tax, employees paid their taxes directly to the government—often as a lump sum at year’s end. The pay-as-you-go system emerged during World War I, when the U.S. government sought to fund the war effort without relying solely on borrowing. Employers began withholding taxes from paychecks, a practice that evolved into the modern payroll system. This shift wasn’t just about revenue; it was a social contract. By automating tax collection, the government reduced the burden on individuals to calculate and remit taxes, while employers gained a structured way to manage compensation.
Table of Contents
- The Complete Overview of What Is the Difference Between Gross Pay and Net Pay
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can my net pay ever be higher than my gross pay?
- Q: Why does my net pay change even if my gross pay stays the same?
- Q: How can I estimate my net pay before accepting a job?
- Q: Are there deductions that don’t reduce my net pay?
- Q: What happens if my employer withholds too much tax from my paycheck?
- Q: How do bonuses affect the difference between gross and net pay?
- Q: Can I negotiate my net pay instead of gross pay?
- Q: What’s the biggest misconception about gross vs. net pay?
- Q: How do international payrolls handle the difference between gross and net pay?
The evolution of what is the difference between gross pay and net pay also reflects broader economic changes. The introduction of Social Security (1935) and Medicare (1965) added new deductions, while employer-sponsored benefits like 401(k) plans (popularized in the 1980s) created voluntary deductions that further shrunk net pay. Today, the system is a patchwork of federal, state, and local rules, with additional layers from industry-specific regulations (e.g., union contracts) and personal financial strategies (e.g., Roth IRA contributions). The result? A paycheck that’s as much a document of economic policy as it is a record of your labor.
Core Mechanisms: How It Works
The mechanics of converting gross pay to net pay begin with the W-4 form, which employees fill out to determine how much tax should be withheld. This form calculates federal income tax based on your claimed allowances, filing status, and any additional withholdings you request. For example, claiming zero allowances means more is withheld upfront, potentially leading to a tax refund later—but also a smaller paycheck now. State taxes follow a similar process, though some states (like Texas) have none, while others (like New York) impose progressive rates. Social Security and Medicare taxes are flat-rate deductions: 6.2% for Social Security (capped at $168,600 in 2024) and 1.45% for Medicare (with no cap, though high earners pay an extra 0.9%).
Beyond mandatory deductions, employers may withhold voluntary contributions like health insurance premiums, retirement plan matches, or garnishments for debts like student loans. Each of these reduces your net pay, but they also provide tangible benefits—healthcare coverage, tax-deferred savings, or debt repayment. The critical takeaway is that what is the difference between gross pay and net pay isn’t just about taxes; it’s about trade-offs. A higher gross salary might be meaningless if your net pay is eaten up by taxes and fees, while a lower gross salary with smart deductions could leave you with more disposable income. Understanding these mechanics allows you to negotiate not just salary, but the entire compensation package.
Key Benefits and Crucial Impact
The clarity that comes from grasping what is the difference between gross pay and net pay extends beyond your bank account. It empowers you to make informed decisions about job offers, tax planning, and long-term financial health. For instance, two identical job offers might appear equal on paper, but one could include a 401(k) match that effectively boosts your net worth over time. Similarly, understanding how deductions work can help you avoid surprises during tax season—whether it’s an unexpected refund or a bill you weren’t prepared for. The impact isn’t just financial; it’s psychological. Knowing exactly how much you’ll take home reduces stress and allows for better budgeting, saving, and investing.
For employers, the distinction is equally critical. Payroll accuracy affects employee satisfaction, tax compliance, and even legal exposure. Missteps in calculating net pay can lead to disputes, audits, or even lawsuits. Conversely, transparent communication about what is the difference between gross pay and net pay builds trust and helps employees feel secure in their compensation. In an era where remote work and gig economies blur traditional payroll lines, this clarity is more important than ever.
"Net pay isn’t just a number—it’s the foundation of your financial independence. The more you understand the deductions that shrink your gross salary, the better you can negotiate, save, and invest. Ignore this difference, and you’re leaving money on the table—or worse, paying more than you owe."
— Sarah Johnson, Certified Public Accountant and Payroll Specialist
Major Advantages
- Financial Planning: Knowing your net pay allows you to budget accurately, avoiding overdrafts or emergency debt. For example, if your gross salary is $75,000 but your net pay is $55,000 after taxes and benefits, you can plan for a $20,000 shortfall in discretionary spending.
- Tax Optimization: Adjusting your W-4 withholdings or contributing to tax-advantaged accounts (like a 401(k) or HSA) can legally reduce your taxable income, increasing your net take-home pay.
- Job Negotiation Leverage: Salary discussions should always consider net pay. A $10,000 raise might sound great, but if it pushes you into a higher tax bracket or reduces employer-sponsored benefits, your net gain could be minimal—or even negative.
- Avoiding Surprises: Understanding deductions prevents sticker shock during tax season. For instance, self-employed individuals must pay both employer and employee portions of Social Security and Medicare, which can significantly reduce net earnings if not accounted for.
- Retirement Security: Voluntary deductions like 401(k) contributions reduce net pay now but compound into substantial retirement savings over time. Even small increases in contribution percentages can have outsized long-term benefits.

Comparative Analysis
| Gross Pay | Net Pay |
|---|---|
| Total compensation before deductions (salary + bonuses + overtime). | Amount received after all taxes and deductions (what you actually take home). |
| Used for tax filings (e.g., W-2 forms) and benefits calculations. | Used for budgeting, bill payments, and discretionary spending. |
| Fixed by employer agreement (contract, offer letter). | Variable based on taxes, benefits, and personal deductions. |
| Does not reflect real-world purchasing power. | Directly impacts your financial capacity and savings potential. |
Future Trends and Innovations
The landscape of what is the difference between gross pay and net pay is evolving with technology and shifting economic priorities. Automated payroll systems now use AI to calculate deductions in real time, reducing errors and providing employees with instant net pay estimates. Blockchain-based payroll platforms are emerging, offering transparency and faster payouts, particularly in global or gig economies. Meanwhile, the rise of "benefits as compensation" (e.g., student loan repayment assistance, mental health stipends) is blurring the lines between gross and net pay, as these perks may not appear on a traditional paycheck but still reduce out-of-pocket expenses.
Legislative changes are also reshaping the equation. For example, proposals to simplify tax brackets or eliminate certain payroll taxes could alter net pay calculations. Remote work trends are pushing states to reconsider tax residency rules, potentially allowing employees to optimize their tax burden by choosing lower-tax jurisdictions. As these trends unfold, the ability to navigate what is the difference between gross pay and net pay will become even more critical—a skill that separates savvy earners from those who leave money unclaimed.

Conclusion
The gap between gross pay and net pay isn’t a flaw in the system—it’s the system itself. Understanding what is the difference between gross pay and net pay isn’t just about crunching numbers; it’s about reclaiming control over your financial destiny. Whether you’re evaluating a job offer, planning for retirement, or simply trying to make ends meet, this knowledge is the difference between reacting to your paycheck and optimizing it. The next time you glance at your pay stub, ask yourself: How much of this is truly mine? The answer lies in the deductions, the taxes, and the choices you make before the money even hits your account.
For employers, the message is equally clear: transparency about pay structures builds trust and attracts top talent. For employees, the takeaway is actionable: negotiate for net impact, not just gross figures, and treat your paycheck as a financial tool, not just a deposit. In an era where economic uncertainty is the norm, mastering this difference isn’t optional—it’s essential.
Comprehensive FAQs
Q: Can my net pay ever be higher than my gross pay?
A: No, net pay will always be less than or equal to gross pay because it represents the amount remaining after deductions. However, certain refunds (e.g., tax over-withholdings, employer reimbursements) or bonuses paid in lump sums might temporarily increase your cash flow, but these are not part of your regular net pay calculation.
Q: Why does my net pay change even if my gross pay stays the same?
A: Net pay fluctuations occur due to changes in tax withholdings (e.g., life events like marriage or parenthood), adjustments to benefits (e.g., switching health insurance plans), or variable deductions (e.g., union dues, student loan payments). Even cost-of-living adjustments or inflation can indirectly affect net pay if they alter tax brackets.
Q: How can I estimate my net pay before accepting a job?
A: Use an online paycheck calculator (like those from ADP or SmartAsset) to input your gross salary, location, and potential deductions. Request a paycheck preview from the employer during negotiations, or ask for a detailed breakdown of their payroll policies. For freelancers or contract workers, account for self-employment taxes (15.3%) and quarterly estimated payments.
Q: Are there deductions that don’t reduce my net pay?
A: Some deductions provide a net benefit even if they reduce your gross-to-net conversion. For example, contributions to a 401(k) or IRA lower your taxable income, potentially reducing your tax burden. Similarly, health savings account (HSA) contributions offer triple tax advantages (pre-tax deductions, tax-free growth, and tax-free withdrawals for medical expenses). These are "net-positive" deductions because they save you more in taxes than they cost in reduced take-home pay.
Q: What happens if my employer withholds too much tax from my paycheck?
A: If your employer withholds more than your actual tax liability, you’ll receive a refund when you file your taxes. While this might seem like "free money," it’s essentially an interest-free loan to the government. To avoid over-withholding, adjust your W-4 allowances or submit a new form annually. Conversely, under-withholding can lead to penalties, so use the IRS Tax Withholding Estimator to fine-tune your withholdings.
Q: How do bonuses affect the difference between gross and net pay?
A: Bonuses are typically added to your gross pay and subject to the same deductions as your regular salary. However, some employers offer "net bonuses" (already taxed) or "gross bonuses" (taxed at year-end). The latter can be advantageous if you’re in a lower tax bracket at year-end, but it requires careful planning to avoid surprises. Always clarify how bonuses are structured during negotiations.
Q: Can I negotiate my net pay instead of gross pay?
A: Yes, and it’s often a smarter strategy. For example, negotiating a lower gross salary in exchange for a higher 401(k) match or flexible spending account contributions can increase your net take-home pay. Similarly, requesting a signing bonus (taxed differently than salary) or relocation assistance can boost your effective compensation without inflating your taxable income.
Q: What’s the biggest misconception about gross vs. net pay?
A: The biggest myth is that gross pay is what matters most. In reality, net pay is what funds your lifestyle, savings, and investments. Many job seekers focus solely on gross salary, only to discover their net pay is insufficient after taxes and living costs. Always ask for a net pay estimate or use a calculator to compare offers fairly.
Q: How do international payrolls handle the difference between gross and net pay?
A: International payrolls vary widely. Some countries (like Germany or Sweden) have progressive tax systems with high social contributions, while others (like the UAE) have no income tax. Remote workers must navigate double taxation treaties, local payroll laws, and currency exchange impacts on net pay. Employers often use global payroll providers to manage these complexities, but employees should clarify how their compensation will be taxed and converted.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Bevvy.